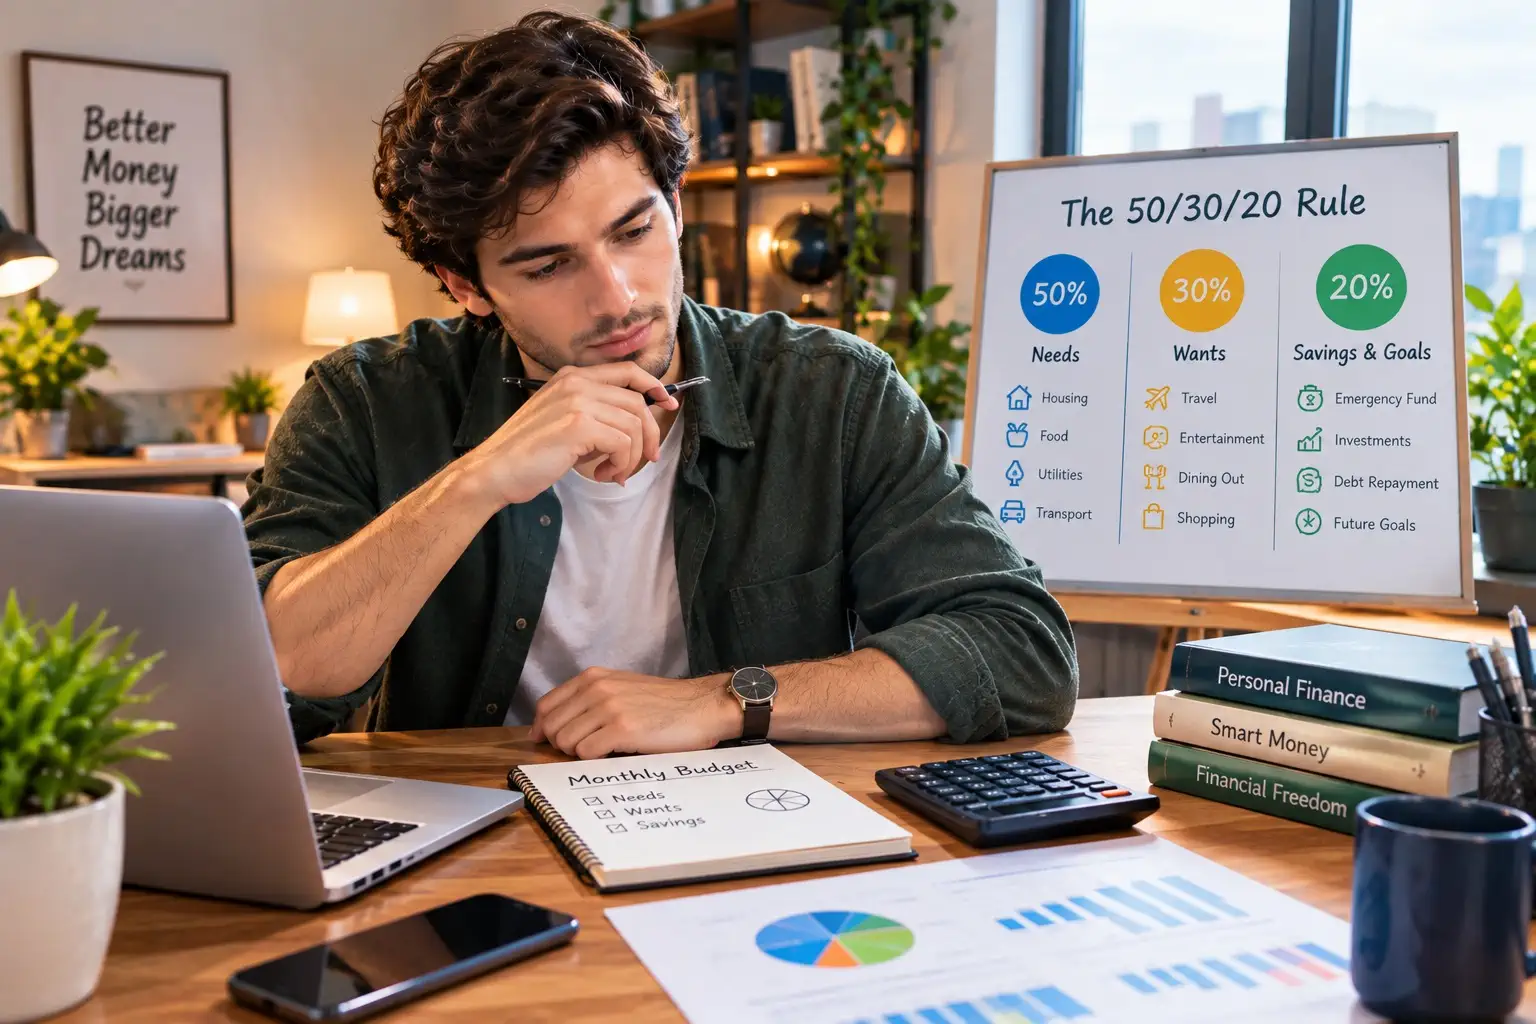
The 50/30/20 budget rule is a simple budgeting framework that divides after-tax income into three broad categories: needs, wants and savings or debt payments.
Instead of tracking every individual purchase from the beginning, the method gives you a high-level framework for deciding where your money should go.
The percentages are a guideline rather than a universal requirement. Housing costs, income, debt, family size, location, and financial goals can all affect what a realistic budget looks like.
You do not have to hit exactly 50%, 30% and 20% every month. The goal is to create a spending plan that fits your circumstances and helps you make progress toward your financial priorities.
In This Guide
- What Is the 50/30/20 Rule?
- How Does It Work?
- What Counts as Needs?
- What Counts as Wants?
- What Counts as Savings?
- 50/30/20 Example
- How Debt Payments Fit In
- How to Adjust the Rule
- What If 50% Is Not Enough for Needs?
- What If You Can Save More Than 20%?
- Common Mistakes
- How to Start Using It
- Final Thoughts
What Is the 50/30/20 Budget Rule?
The 50/30/20 budget rule is a budgeting framework that divides your after-tax income into three broad categories.
| Category | Guideline | General Purpose |
|---|---|---|
| Needs | 50% | Essential living expenses |
| Wants | 30% | Non-essential spending |
| Savings / Debt | 20% | Savings, investing and certain debt payments |
The framework is designed to make budgeting easier to understand without requiring a detailed category for every purchase.
How Does the 50/30/20 Rule Work?
Start with your monthly after-tax income — the money you actually receive after applicable payroll deductions and taxes.
You then use the 50/30/20 framework as a starting point for allocating that income.
For example, if your monthly after-tax income is $4,000:
| Category | Percentage | Example Amount |
|---|---|---|
| Needs | 50% | $2,000 |
| Wants | 30% | $1,200 |
| Savings / Debt | 20% | $800 |
This is a simplified example. Your actual allocation may look very different depending on your financial situation.
What Counts as Needs?
Needs are expenses that are important for basic living and financial obligations.
Examples can include:
- Housing
- Basic utilities
- Groceries
- Transportation needed for work or essential activities
- Basic insurance
- Minimum required debt payments
- Essential medical expenses
- Other necessary household expenses
Not every expense is clearly a need or a want. For example, transportation may be essential in one person's situation and optional in another.
What Counts as Wants?
Wants are expenses that improve your lifestyle but are not strictly necessary for basic needs.
Examples can include:
- Restaurant meals
- Entertainment
- Streaming subscriptions
- Hobbies
- Non-essential shopping
- Travel
- Premium upgrades
Wants are not automatically bad spending. A sustainable budget should leave room for some enjoyable spending when your financial situation allows it.
What Counts as Savings?
The savings portion can include several different financial goals.
Depending on your situation, it may include:
- Emergency fund contributions
- Retirement savings
- Long-term investing
- Short-term savings goals
- Sinking funds
- Additional debt payments
One useful approach is to give each part of your savings a specific purpose rather than treating every dollar as one large pool.
50/30/20 Budget Example
Let's look at a hypothetical household with $5,000 in monthly after-tax income.
| Category | Target | Monthly Amount |
|---|---|---|
| Needs | 50% | $2,500 |
| Wants | 30% | $1,500 |
| Savings / Debt | 20% | $1,000 |
| Total | 100% | $5,000 |
Again, these amounts are illustrative rather than recommended targets for every household.
How Do Debt Payments Fit Into the 50/30/20 Rule?
Debt can make the framework more complicated.
Minimum required debt payments are generally treated as necessary obligations, while extra payments toward debt may be considered part of the financial-goals or savings/debt portion.
The exact classification is less important than making sure your debt payments are included in your overall plan.
If you have expensive high-interest debt, you may choose to prioritize paying it down before increasing certain forms of long-term saving or investing.
A budgeting framework should help you make better financial decisions. It should not force you into percentages that prevent you from dealing with important financial obligations.
How to Adjust the 50/30/20 Rule
Real-life budgets rarely fit perfectly into neat percentages.
You may need to adjust the framework because of:
- High housing costs
- Variable income
- Student loan payments
- Credit card debt
- Childcare expenses
- Medical costs
- Aggressive savings goals
- Temporary financial changes
For one person, a 60/20/20 budget may be more realistic. Someone else may use 55/20/25 or another combination.
The important thing is to understand where your money is going and intentionally direct it toward your priorities.
What If 50% Is Not Enough for Your Needs?
Housing and other essential expenses can consume a large portion of income, especially in expensive areas.
If your needs are already above 50%, do not assume that your budget has failed.
Instead:
- Calculate your actual essential expenses.
- Identify expenses that may be reduced.
- Review optional spending.
- Set a realistic savings target.
- Revisit the budget as your circumstances change.
A realistic budget is more useful than a theoretically perfect budget that cannot be maintained.
What If You Can Save More Than 20%?
If your essential expenses and lifestyle costs are comfortably covered, you may have room to save more than 20%.
Additional savings could potentially be directed toward:
- Emergency savings
- Retirement accounts
- Long-term investments
- A home purchase
- Education
- Other financial goals
The 20% figure should not be treated as a maximum. If your circumstances allow for a higher savings rate, you can adapt the framework.
Common 50/30/20 Budgeting Mistakes
Treating the percentages as strict rules
The framework is a guideline. Your actual percentages may need to be different.
Forgetting irregular expenses
Annual insurance payments, repairs, gifts, holidays and other irregular costs can disrupt a budget if they are ignored.
Calling everything a need
Some expenses are important but can still contain optional components. Reviewing them carefully can reveal opportunities to save.
Ignoring debt
Minimum payments and additional debt reduction should be incorporated into the financial plan.
Creating a budget without tracking actual spending
A budget works best when you compare your plan with what you actually spend.
Cutting all enjoyable spending
A budget that leaves no room for reasonable discretionary spending can become difficult to maintain.
How to Start Using the 50/30/20 Rule
Step 1: Calculate your after-tax income
Add up the income you actually receive during a typical month.
Step 2: List your essential expenses
Write down housing, utilities, groceries, transportation, insurance, minimum debt payments and other essential costs.
Step 3: Review discretionary spending
Identify restaurants, entertainment, subscriptions, shopping, hobbies and other non-essential purchases.
Step 4: Set savings targets
Decide how much you want to put toward emergency savings, investing, retirement, sinking funds or additional debt payments.
Step 5: Compare your actual numbers
See how your current spending compares with the 50/30/20 framework.
Step 6: Adjust gradually
Instead of changing everything at once, identify one or two categories where a realistic change could make the biggest difference.
Step 7: Review your budget regularly
Income, bills, goals and priorities change. Review your budget periodically and adjust it accordingly.
50/30/20 Budget Checklist
- □ Calculate monthly after-tax income.
- □ List essential expenses.
- □ Separate needs from wants.
- □ Calculate current savings.
- □ Include debt payments.
- □ Identify irregular expenses.
- □ Set realistic savings goals.
- □ Compare actual spending with your plan.
- □ Adjust the percentages when necessary.
Final Thoughts
The 50/30/20 budget rule can be a useful starting point for people who want a simple way to organize their money.
Its biggest advantage is simplicity: instead of trying to create a perfect budget immediately, you can start by thinking about needs, wants and financial goals.
But the percentages should not become a source of stress. Your housing costs, income, debt, responsibilities and financial goals may require a different allocation.
The best budget is one you understand, can maintain and can adjust as your financial situation changes.
Calculate your after-tax income, categorize your major expenses, identify your savings goals and then use 50/30/20 as a starting framework rather than a rigid rule.