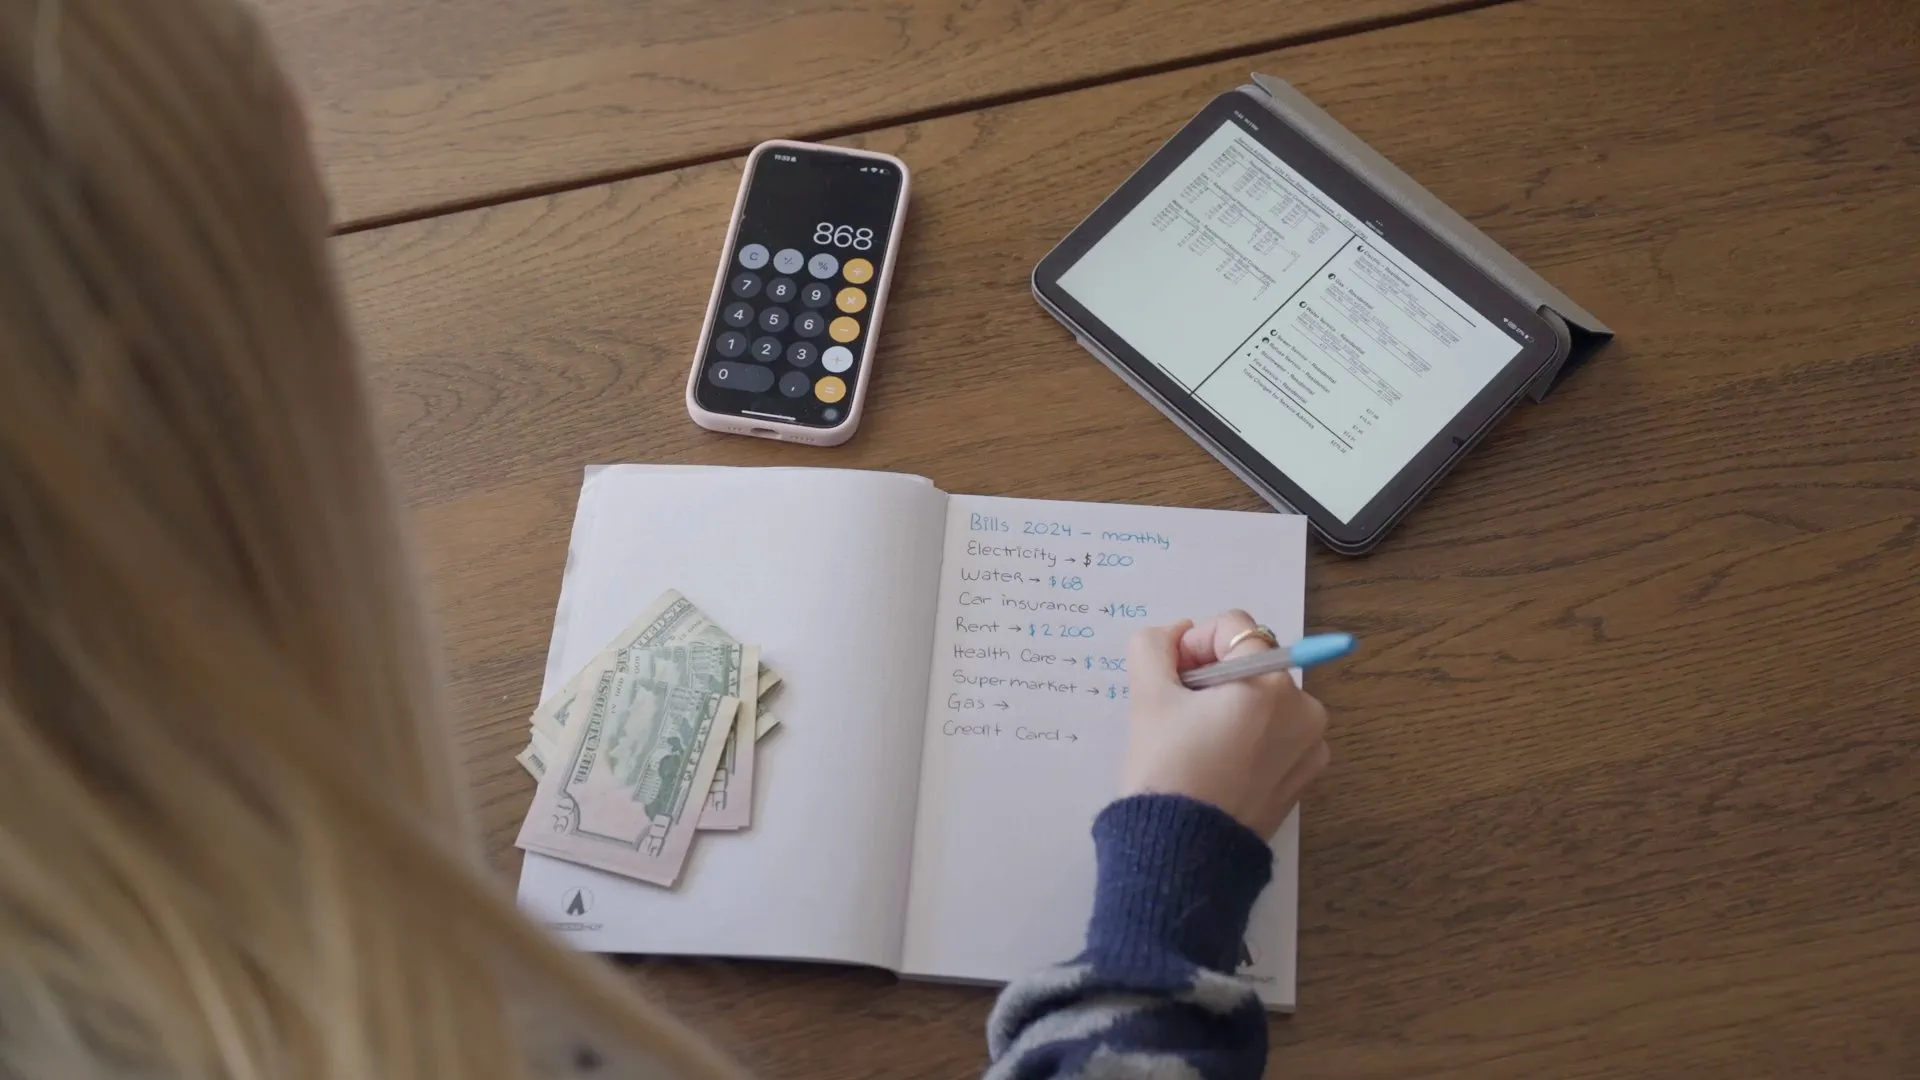
Zero-based budgeting is a budgeting method where you assign every dollar of expected income to a specific purpose before the month begins.
The goal is not to spend all your money carelessly. Instead, every dollar is given a job, such as paying bills, buying groceries, saving for an emergency, reducing debt or working toward a future financial goal.
This approach can make your money easier to organize because it gives you a clear plan for both spending and saving.
A zero-based budget should finish at zero after planned expenses, savings, debt payments and other assignments are included. It does not mean your bank account should be empty.
What Is Zero-Based Budgeting?
Zero-based budgeting is a method in which your planned income minus your planned assignments equals zero.
The basic formula is:
Planned assignments may include bills, groceries, transportation, savings, debt payments, investing, personal spending and money reserved for future expenses.
For example, if your expected monthly income is $4,000, you create a plan that assigns the full $4,000 to different categories.
The money may be assigned to current expenses, savings accounts, debt payments or future spending categories. The important part is that the entire amount has a purpose.
How Does Zero-Based Budgeting Work?
With a zero-based budget, you do not wait until the end of the month to see what is left over. You make decisions about your money before you spend it.
A typical process looks like this:
- Estimate your income for the month.
- List essential expenses.
- Add flexible spending categories.
- Include savings contributions.
- Include debt payments.
- Set aside money for irregular expenses.
- Assign any remaining money to a useful category.
If your planned assignments are higher than your income, you need to reduce expenses, adjust savings contributions, increase income or change your timeline.
Benefits of a Zero-Based Budget
Zero-based budgeting can be useful for people who want more control over where their money goes.
Greater awareness
Assigning money to categories makes it easier to see how much you plan to spend on different needs and wants.
Clear financial priorities
You can give savings, debt reduction or other financial goals a place in your monthly plan.
Less unplanned spending
A written plan can help you pause before making purchases that were not included in your budget.
Better preparation
You can create categories for annual bills, repairs, gifts, travel and other predictable expenses.
Easier progress tracking
Comparing planned amounts with actual spending helps you understand what needs to change.
How to Create a Zero-Based Budget Step by Step
Creating your first zero-based budget may take some time but the process becomes easier after you have collected your regular income and expense information.
Step 1: Choose a budgeting period
Many people create a monthly budget because bills and income are often organized around monthly schedules. You can also use weekly or biweekly planning if that better matches your cash flow.
Step 2: Gather your financial information
Review recent bank statements, bills, receipts, subscriptions, debt statements and savings contributions.
Step 3: Estimate your income
Use a realistic income estimate. If your income changes from month to month, consider using a conservative estimate and updating the budget when actual income becomes clear.
Step 4: Add essential expenses
Include housing, utilities, groceries, transportation, insurance, required debt payments and other essential costs.
Step 5: Add flexible spending
Include categories such as dining out, entertainment, clothing, hobbies and personal spending.
Step 6: Assign money to savings goals
Add emergency savings, planned purchases, retirement contributions or other goals that fit your financial situation.
Step 7: Give every remaining dollar a purpose
Continue assigning money until your planned income and planned assignments are equal.
Calculate Your Monthly Income
Start with the money you realistically expect to receive during the budgeting period.
Depending on your circumstances, income may include:
- Employment income
- Freelance or self-employment income
- Regular business income
- Certain recurring benefits
- Other predictable income sources
Avoid relying on uncertain bonuses, irregular gifts or possible future income to cover essential bills.
If your income is irregular, create a flexible budget and update it when money actually arrives.
List Your Monthly Expenses
Divide your expenses into useful categories. Your categories should be detailed enough to guide decisions but simple enough to maintain.
Fixed expenses
Fixed expenses are costs that usually remain similar from month to month, such as rent, insurance or a regular loan payment.
Variable expenses
Variable expenses change based on usage or behavior. Examples include groceries, transportation, utilities and entertainment.
Periodic expenses
Periodic expenses do not occur every month but should still be included in your plan. Examples include annual memberships, vehicle maintenance, gifts and insurance renewals.
Include Savings and Debt Payments
One of the main benefits of zero-based budgeting is that savings and debt payments are treated as planned assignments rather than whatever happens to remain at the end of the month.
Depending on your priorities, your budget may include:
- Emergency fund contributions
- Short-term savings
- Sinking funds
- Retirement contributions
- Additional debt payments
- Money for future investments
If you are building an emergency fund, you can review our emergency fund guide for additional planning ideas.
You can also learn how to organize planned expenses through sinking funds .
Zero-Based Budget Example
The following example uses an illustrative monthly income of $4,000.
| Category | Planned Amount |
|---|---|
| Housing | $1,200 |
| Utilities | $250 |
| Groceries | $450 |
| Transportation | $300 |
| Insurance | $200 |
| Debt Payments | $350 |
| Emergency Savings | $400 |
| Retirement Savings | $300 |
| Sinking Funds | $200 |
| Personal Spending | $150 |
| Dining and Entertainment | $100 |
| Miscellaneous | $100 |
| Total Assigned | $4,000 |
This example is for educational purposes only. Actual amounts should be based on your income, obligations, location, household needs and financial priorities.
Plan for Irregular Expenses
A budget can fail when it only includes monthly bills and ignores expenses that happen occasionally.
To prepare for irregular expenses, estimate the yearly cost and divide it by the number of months available.
For example, if you expect a $600 annual expense, you could plan to reserve approximately $50 per month.
Common sinking-fund categories include:
- Vehicle repairs
- Home maintenance
- Holiday gifts
- School or education costs
- Medical or dental expenses
- Annual subscriptions
- Travel and holidays
Adjust Your Budget During the Month
A zero-based budget is a plan, not a rigid rule that can never change.
If you spend less than expected in one category, you may be able to assign the difference to savings, debt payments or another priority.
If an expense is higher than expected, review the rest of your plan and make a deliberate adjustment.
For example, you might:
- Reduce discretionary spending.
- Move money from a flexible category.
- Delay a nonessential purchase.
- Adjust a savings contribution temporarily.
- Revisit the next month's budget.
The goal is to make an informed decision instead of allowing spending to happen without a plan.
Common Zero-Based Budgeting Mistakes
Forgetting irregular expenses
Annual bills, repairs and gifts should have a place in your financial plan.
Using unrealistic estimates
If your grocery or transportation estimate is too low, the budget may become difficult to maintain.
Leaving no flexibility
A small flexible category can help you manage unexpected changes without rebuilding the entire budget.
Treating savings as optional
If savings are important to your goals, include them as planned assignments.
Making the system too complicated
Too many categories can make budgeting exhausting. Use a level of detail you can maintain consistently.
Not reviewing actual spending
Compare your plan with your real transactions so that future budgets become more accurate.
Tools for Zero-Based Budgeting
You do not need an expensive application to begin. Choose a tool that makes it easy to record income, assign categories and review progress.
Possible options include:
- A simple spreadsheet
- A budgeting notebook
- A personal finance application
- A digital calendar for bill reminders
- A banking dashboard
The best system is one you can update regularly and understand without confusion.
Zero-Based Budgeting Checklist
- □ Estimate your total income.
- □ List all essential expenses.
- □ Add flexible spending categories.
- □ Include savings contributions.
- □ Include debt payments.
- □ Plan for irregular expenses.
- □ Assign every dollar a purpose.
- □ Compare planned and actual spending.
- □ Adjust the plan when circumstances change.
Final Thoughts
Zero-based budgeting can help you become more intentional with your money by giving every dollar a clear purpose.
The process begins with realistic income estimates, a complete list of expenses and clearly defined financial priorities.
Remember that a zero-based budget does not mean spending everything. It means assigning money to useful categories, including savings, debt payments and future expenses.
Start with a simple version, review it regularly and improve it as you learn more about your spending habits.
Write down your expected income for the next month. Then list your bills, spending categories, savings goals and debt payments until every dollar has a purpose.